CBIC Circular 266/12/2026-GST dated 28 October 2026 settles six service-side GST doubts, based on the 57th GST Council meeting. Here is what each one means and who should check their invoices.
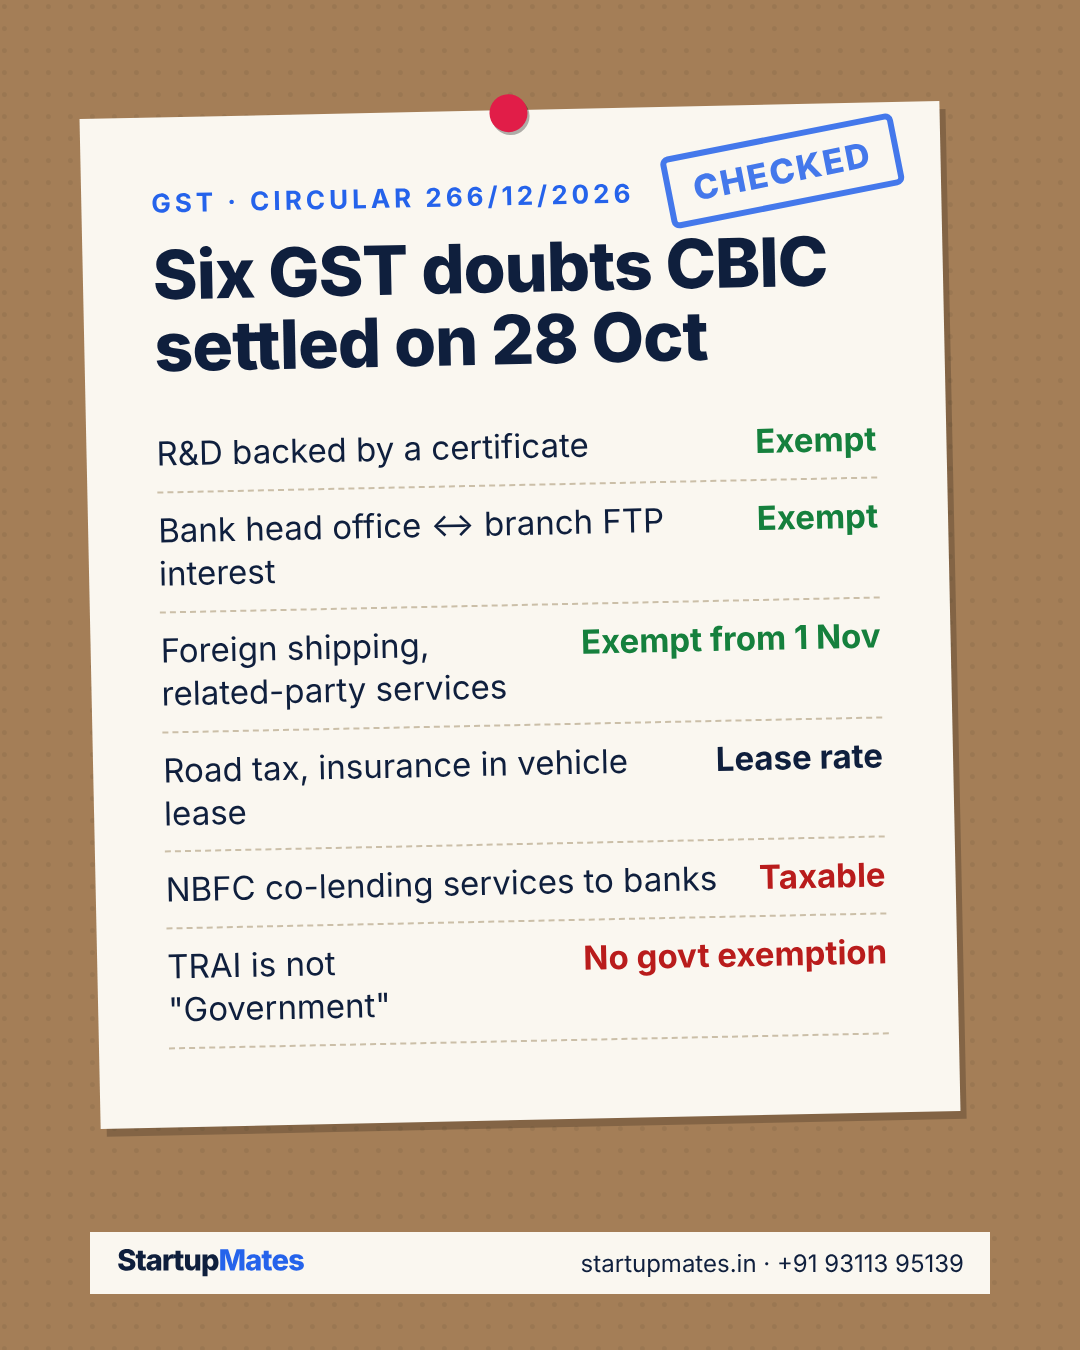
CBIC has issued Circular No. 266/12/2026-GST dated 28 October 2026 under section 168(1) of the CGST Act, following the recommendations of the 57th GST Council meeting. It clarifies six service-side questions.
The six clarifications
- Research and development: the R&D exemption (Entry 44A) can be supported by a certificate from the head of the government entity, research association, university or institution, so that R&D work is not treated as taxable consultancy.
- Foreign shipping companies: services imported by an Indian establishment from a related person or overseas establishment without consideration are regularised "as is where is" for 1 July 2017 to 31 October 2026, and exempt from 1 November 2026.
- Motor vehicle leasing: registration charges (including road tax), insurance, FASTag and similar recoveries are part of the leasing supply and taxed at the leasing rate.
- TRAI: it is not "Government" under section 2(53), so exemptions meant only for Government do not apply.
- Bank fund transfer pricing: notional interest between a bank's head office and branches is treated as interest and is exempt.
- NBFC co-lending: sourcing, KYC, appraisal, servicing and collection services an NBFC provides to a bank are taxable, valued as per their contract.
What to do
- Lessors and NBFCs: check that your invoices charge GST on the full value as clarified.
- R&D providers: keep the institution head's certificate on file with each contract.
- Unsure how this affects you? Call or WhatsApp +91 93113 95139 for a free consultation.
Sources: Calcguru, CorpLawUpdates, Maritime Gateway, CBIC GST portal
#gst#cbic#circular#nbfc#leasing
Need help with this?
Our experts can handle it for you. The first call is free.